
CIS returns, refunds andreverse charge VAT, handled.
Whether you deduct CIS from subcontractors or have it deducted from you, we file the monthly returns, reclaim what you are owed and keep the reverse charge VAT right on every invoice.
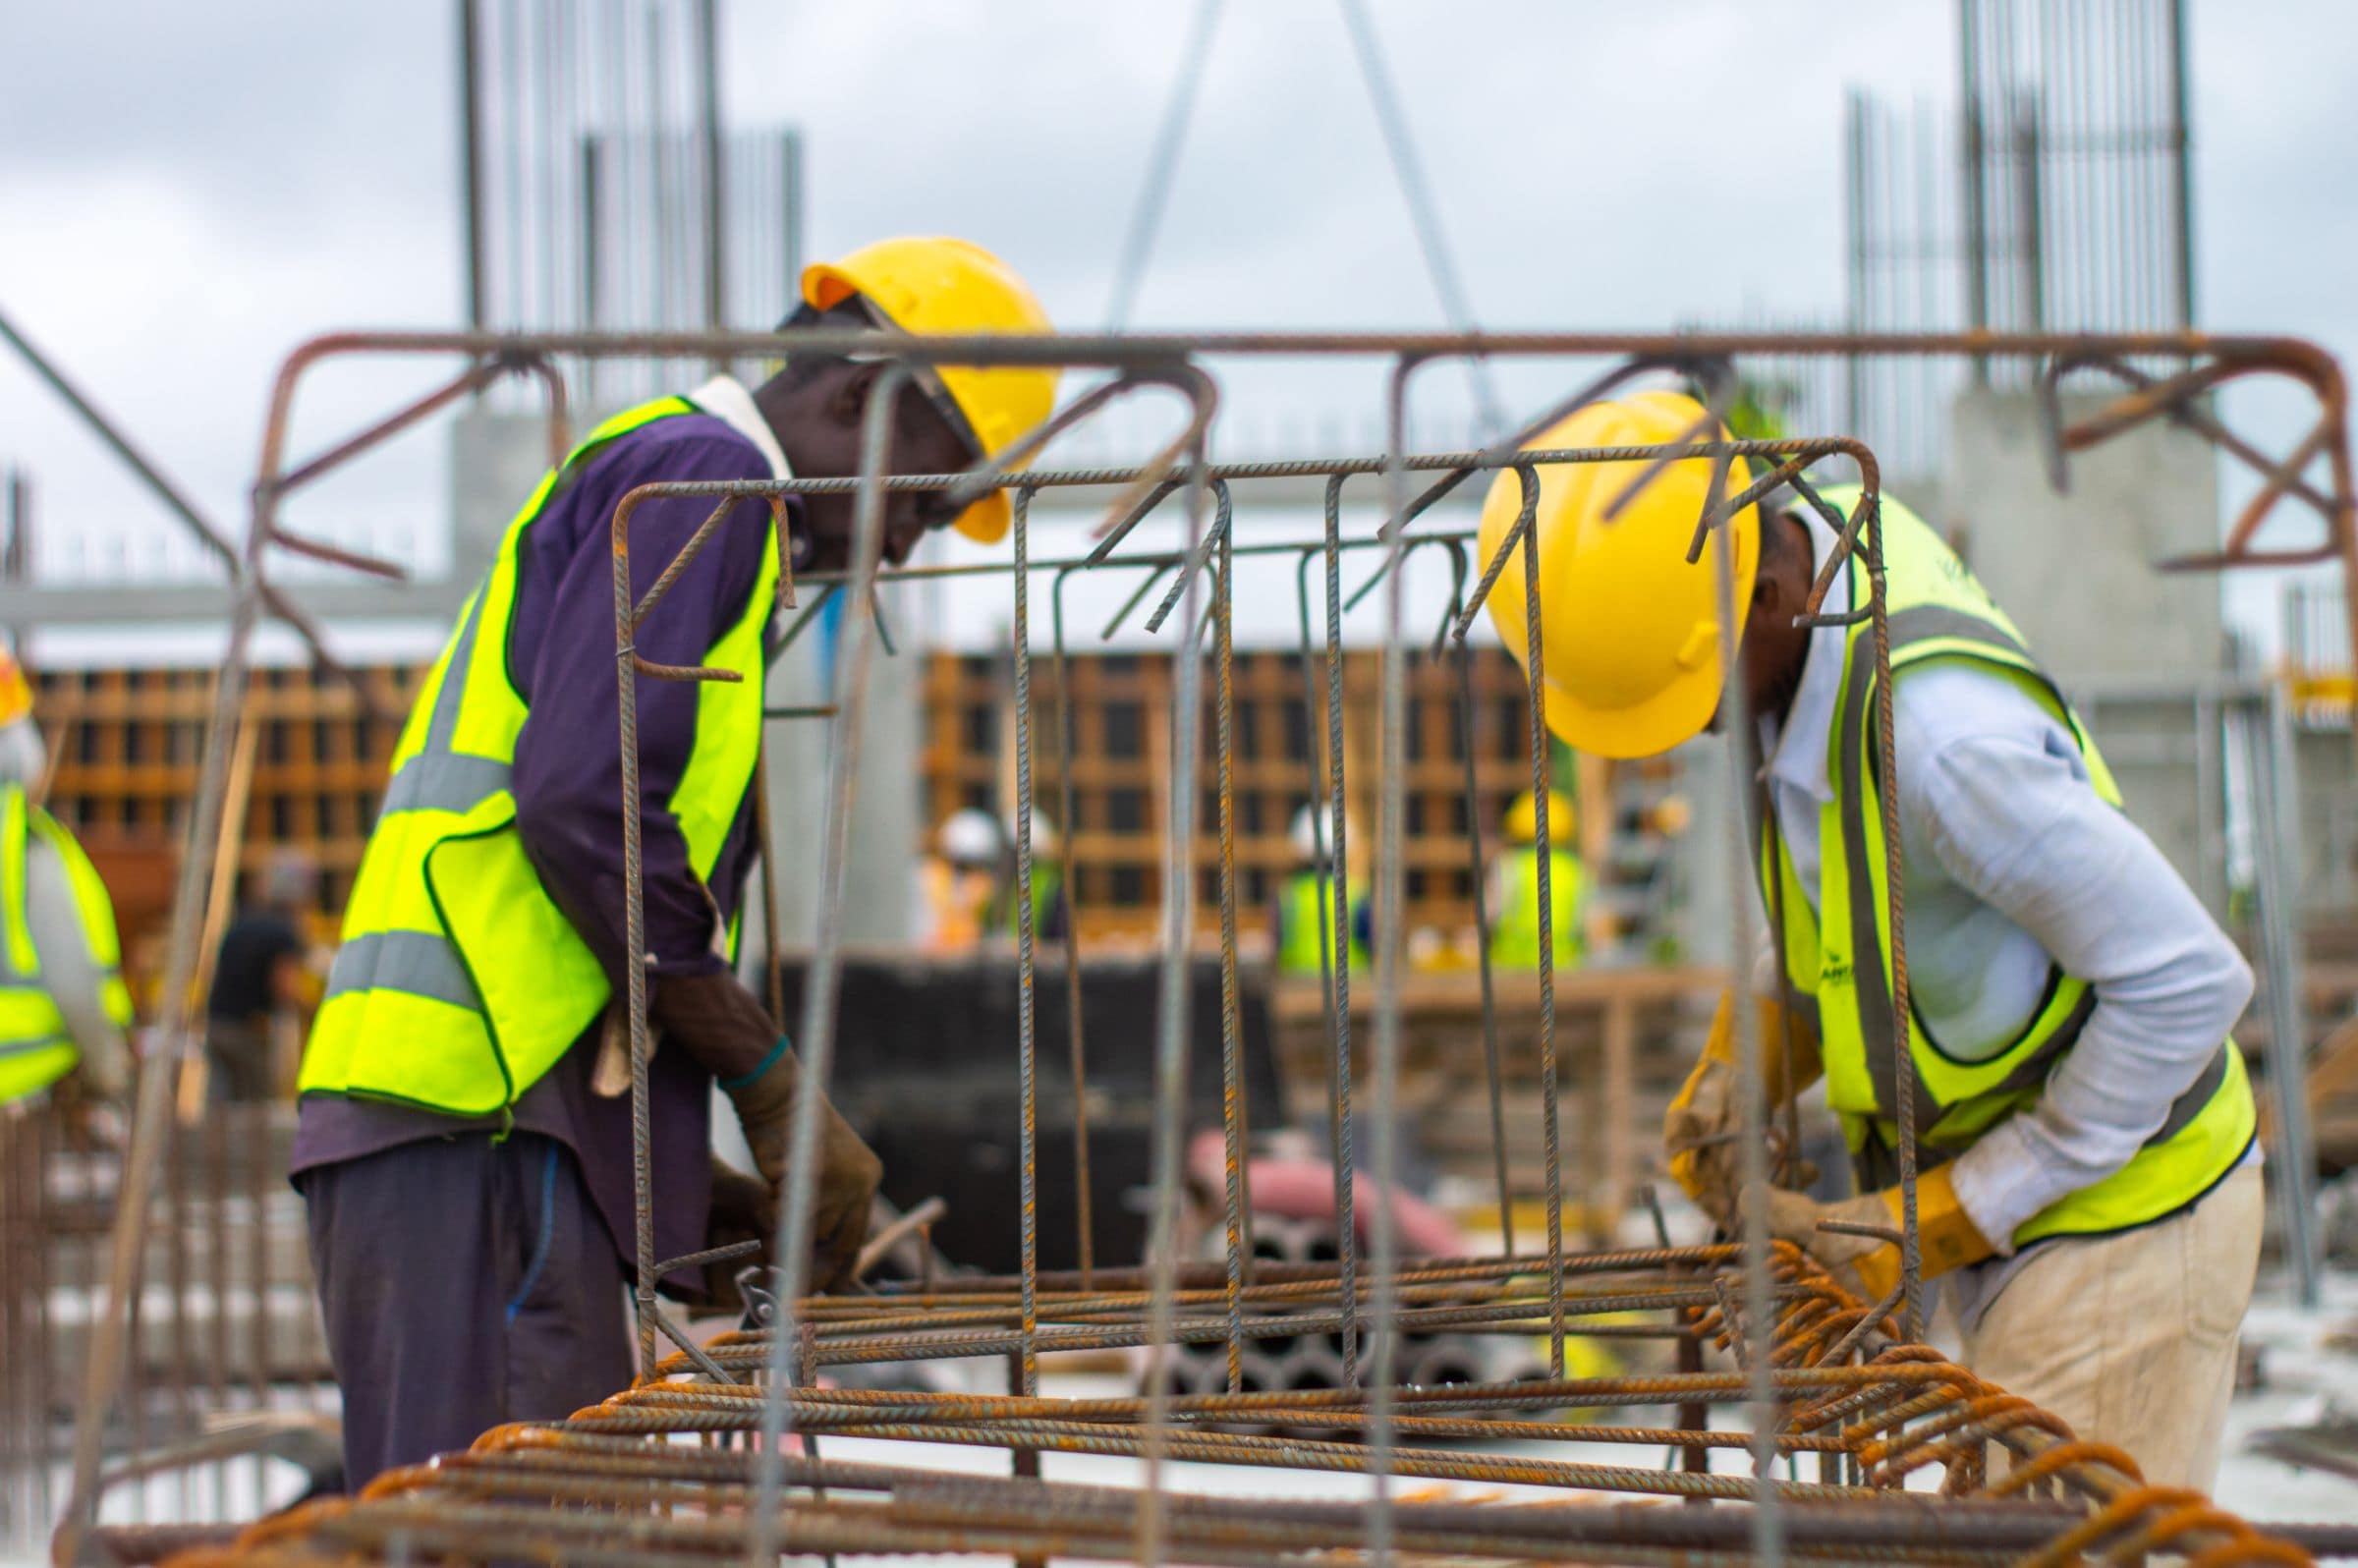
What makes your finances different.
Tax deducted before you see it
Subcontractors lose 20%, or 30% if unverified, of their labour income at source. Reclaiming it, or offsetting it against PAYE for companies, needs accurate statements and a correctly filed return.
Monthly CIS returns with sharp penalties
Contractors must verify every subcontractor and file a return by the 19th of each month. A late return costs £100 immediately, another £200 after two months, then the greater of £300 or 5% of the deductions after six months and again after twelve.
Reverse charge VAT
Since 2021 VAT-registered construction businesses do not charge VAT to other VAT-registered CIS customers; the customer accounts for it. Invoices need specific wording, and cash flow changes.
Retentions and work in progress
Retentions held back for months, stage payments and part-completed jobs make the profit figure in the accounts a judgement, and one HMRC looks at closely.
What we do for you.
- Register you as a CIS contractor, subcontractor or both
- Verify subcontractors with HMRC and file the monthly CIS return by the 19th
- Issue payment and deduction statements to subcontractors
- Reclaim CIS suffered for sole traders through Self Assessment and offset it against PAYE for companies
- Apply for gross payment status once turnover and compliance tests are met
- Prepare VAT returns with the domestic reverse charge applied correctly
- Prepare accounts with work in progress and retentions properly valued
- Run PAYE for employed staff and advise on employment status of labour-only subcontractors
The tax rules that matter here.
- CIS deduction rates
- Contractors deduct 20% from registered subcontractors and 30% from unregistered or unverified ones. Deductions apply to labour only, not materials, and never to VAT.
- Gross payment status
- Subcontractors with a clean compliance record and turnover of at least £30,000 per partner or director (net of materials) can be paid gross. HMRC reviews status annually and can withdraw it for late filings.
- Domestic reverse charge
- For specified construction services between VAT-registered businesses within CIS, the supplier does not charge VAT. The invoice must state that the reverse charge applies and the customer accounts for the VAT on their return.
- Monthly return deadlines
- CIS300 returns are due by the 19th of each month for the previous tax month, even if no payments were made unless HMRC has been told the scheme is inactive. Deductions are paid to HMRC with PAYE by the 22nd.
- Employment status
- Labour-only subcontractors who work set hours under supervision with no financial risk can be employees in HMRC's view, with PAYE and National Insurance due. Each engagement should be assessed.
Rules and rates are those in force for 2026/27 at the time of writing. Check your own position before acting.
Run your own numbers first.
- VAT calculator
Add VAT to a net price, or strip it out of a gross figure.
- Corporation Tax calculator
Corporation Tax on your profit, including marginal relief.
- Self-employed tax calculator
Income tax and National Insurance on sole trader profits.
Worth asking.
Sole traders and partners claim the deductions on their Self Assessment return; the CIS suffered is set against the tax due and any excess refunded after 31 January, or earlier if the return is filed early. Limited companies offset CIS suffered against their monthly PAYE and CIS liabilities through the Employer Payment Summary, and claim any remaining balance after the tax year ends.
Gross payment status means contractors pay you without deducting 20%. You need a clean filing and payment record, a construction business run through a UK bank account, and net turnover of at least £30,000 for a sole trader, or £30,000 per director for a company (or £100,000 in total). It improves cash flow considerably, and we prepare the application.
If you and your VAT-registered customer are both within CIS and the work is a specified construction service, you do not charge VAT; you state on the invoice that the domestic reverse charge applies and the customer accounts for it. Work for end users, private homeowners and non-VAT registered customers is invoiced with VAT as normal.
£100 the day after the deadline, a further £200 after two months, then the higher of £300 or 5% of the deductions after six months and again after twelve. Penalties apply even to nil returns if HMRC expects one, so telling HMRC when you have no subcontractors matters.
Often yes above modest profits, for limited liability on contracts and because companies can offset CIS suffered against PAYE monthly rather than waiting until the year end. The trade-off is more administration and the need to run payroll. We compare both for your figures.
Yes. We obtain the subcontractor records and prior returns, register as your agent for CIS and PAYE, and take over the monthly cycle from the next return.
The services involved
Guides for construction & cis
All articles
VAT & Making Tax Digital
Untangling the Complexity of VAT for UK Small Business Owners
Untangling VAT for UK small business: this guide offers practical advice on VAT schemes, HMRC regulations, and leveraging benefits.
VAT & Making Tax Digital
5 Common VAT Return Mistakes UK Entrepreneurs Make and How to Steer Clear of Them
This article explores common VAT Return Mistakes UK entrepreneurs make, how these errors impact businesses, and strategies to avoid such pitfalls.
Bookkeeping & fees
Keeping Ahead: Accounting Deadlines It’s Crucial For London Businesses To Know
Accounting deadlines in London are essential for businesses to navigate to ensure growth and avoid penalties.